Planning to buy, build or fix up a home in Ahmedabad? We help you find a loan you can repay with ease. You see offers from different lenders and we guide you at each step. The lender gives the final approval.
LOAN AMOUNT
Based on your income
Also depends on your credit score and the value of the home.
INTEREST RATE
Set by the lender
Depends on your profile and the lender’s rules.
TENURE
Up to 30 years
Pick a time that keeps your EMI comfortable.
CHARGES
Clear from day one
We list every fee before you apply.
OVERVIEW
A home loan is money from a bank or finance company that helps you pay for a home. You repay it in monthly payments called EMIs. Each EMI covers part of the loan and the interest.
You can choose a fixed rate, where your EMI stays the same all through. Or you can choose a floating rate, where your EMI can go up or down when lending rates change. The home you buy is the security for the loan.
We help you compare lenders, so you pick a loan that suits your income and your plans. You can apply online or visit us in Ahmedabad.
You can use a home loan to
OUR AHMEDABAD OFFICE
Our Ahmedabad office
OUR AHMEDABAD OFFICE
OUR AHMEDABAD PARTNERS
Talk to us in person or on the phone. We will tell you which lenders can work for you.
BENEFITS
A home loan lets you move in sooner and pay over time.
Under the current income tax rules, you may be able to claim a deduction on the loan you repay and on the interest you pay. Rules can change, so check with a tax advisor.
Lenders set their own rates. We compare them so you can see which one suits your income and credit score.
A longer repayment time, up to 30 years, can make your EMI smaller. You can also move your loan to another lender later, or take extra money on your loan, to match your needs.
Introduce them to us. We will help them with the loan.
ELIGIBILITY
There is no single rule for everyone. Each lender sets its own, so we help you find the lender that suits you.
How much can I borrow?
Your loan amount depends on what you earn and what you already pay each month.
If you have a job, lenders look at your pay, your expenses and your credit score. Each lender has its own rules. We find the one that fits you.
Income proof
Salary slips
Bank statements
Recent months
ID and address proof
Standard papers
Property papers
Documents for the home you want
If you run a business, lenders look at your business papers and your income. Each lender has its own rules. We find the one that fits you.
Income proof
Business and tax records
Financial statements
Your business accounts
Bank statements
Recent months
Property papers
Documents for the home you want
NRIs may be able to get a home loan for a home in India. It depends on the lender. Please speak to our advisor first.
Identity proof
Passport and visa
Income proof
As the lender asks
Bank details
As the lender asks
Property papers
Documents for the home you want
Work out your EMI and get the exact list of papers lenders ask for.
For planning only. Your lender confirms the final EMI.
RATES, FEES AND CHARGES
Interest is not the only cost. Look at every fee before you choose.
Item
Typical
Notes
Interest rate
Set by the lender
Depends on your income, credit score and loan amount
Rate type
Fixed or floating
Floating rates can change when lending rates change
Processing fee
Set by the lender
We share the exact fee upfront
Admin costs
Set by the lender
Ask the lender for the full list
Paying off early
Set by the lender
Check the rules in your loan papers
BEFORE YOU APPLY
Think before you apply. A little planning can save you stress later.
Check your income and spending to see what EMI you can pay.
Borrow what fits your budget, not the most you can get.
ID, income proof, bank statements and property papers.
A good score helps you get better terms.
Read all the charges
Check fees, admin costs and early payoff rules.
Look at the time and the rate type before you decide.
RELATED LOANS
Need help with something else? Take a look.
How we work
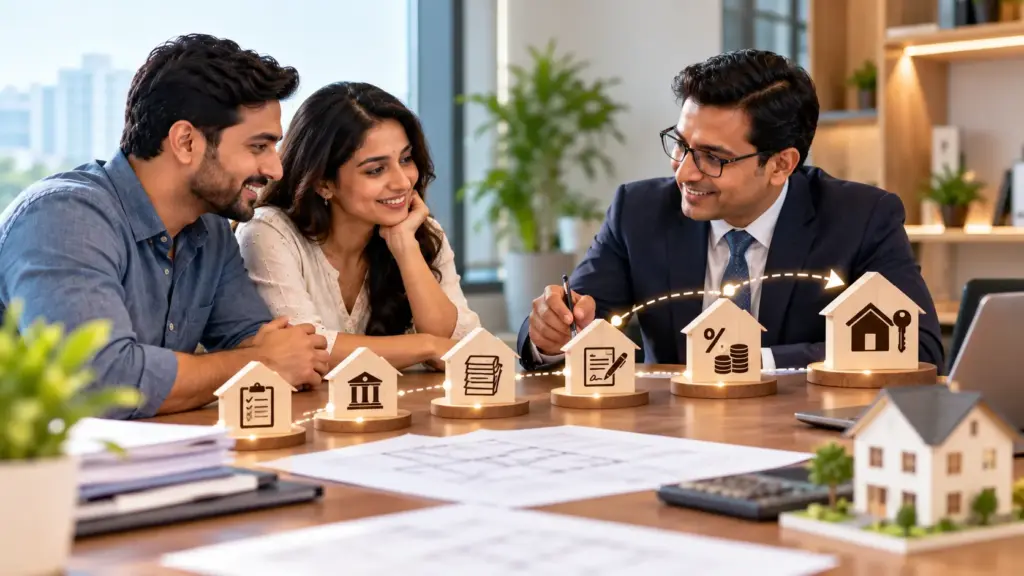
At every step you know what is happening, who is handling it and what you get at the end of it.
01
We review your income, credit history, property and existing loans, and tell you honestly what is possible.
who
You + your advisor
You get
A clear view of what is possible
02
We shortlist the banks and NBFCs whose policies fit your profile, so you apply where approval is likely.
who
You + your advisor
You get
A clear view of what is possible
03
We give you one checklist, collect the papers and check them before the lender sees your file.
who
You + your advisor
You get
A clear view of what is possible
04
We present your case to the chosen lender and handle their questions on your behalf.
who
You + your advisor
You get
A clear view of what is possible
05
We compare the sanction terms and negotiate rate, fees and conditions where possible.
who
You + your advisor
You get
A clear view of what is possible
We follow up on legal, valuation and agreement steps until the money reaches you.
who
You + your advisor
You get
A clear view of what is possible
CASE STUDY
From a client’s own words on our website.
WORKING CAPITAL ENHANCEMENT
A Mumbai-based engineering components manufacturer with ₹60 Cr turnover and 12 years in business. Its existing ₹4 Cr cash credit limit no longer matches its order book.
Our approach: assess the working capital need from audited financials, the stock and debtor cycle, and the order pipeline. Then propose increasing the limit to ₹8 Cr, backed by stock and book debts, with the factory land and building as additional security.
Client
Engineering manufacturer, Mumbai
Turnover
₹60 Cr
Structure
Cash credit enhancement (₹4 Cr → ₹8 Cr)
Security
Factory land & building, valued ~₹12 Cr
Posted on Google
 Dev singh
Trustindex verifies that the original source of the review is Google.
Smooth process along with correct guidancePosted on Google PRATIK SHAHNihal Fintech helped alot throughout the process and provided complete support especially Rajesh More and Niral mehta. Really thanks for helping us throughout and help us to achieve our dream of having house in Mumbai.Posted on Google
 Harsshal GosaviVery professional and reliable finance consultant. Clear guidance, quick response, and transparent process. Highly recommended for loans and financial solutions.Posted on Google
 Vikas Ambade
Trustindex verifies that the original source of the review is Google.
All documentation work was completed on time; thanks for the team.
There is no fixed amount. Each lender sets its own criteria. Your income, expenses, credit score, and repayment capacity determine eligibility.
Home loan rates vary across lenders and change frequently. The rate you get depends on your profile, credit score, loan amount, and lender policies.
Your loan amount depends on your monthly income, existing EMIs, credit score, and the property value. Most lenders use your repayment capacity to calculate eligibility.
Common documents include ID proof, address proof, income proof, bank statements, property documents, and photographs. Self-employed applicants may need business documents and financial statements.
A higher credit score improves your chances of approval and may help you get better terms. A lower score does not guarantee rejection, but it may reduce eligibility.
Yes. Co-applicants, such as a spouse or parent, may increase loan eligibility and the sharing of ownership.
Share a few details and an advisor will call you to check feasibility. Or call us on +91 77009 44833.