Need money for your business but do not want to give property or assets as security? An unsecured loan may help. We guide you from the first call to the final offer, and the lender makes the final decision.
SECURITY
None needed
You do not pledge property or machines.
PAPERS
Simple
Bank statements and tax returns are the main items.
REPAYMENT
Flexible
Options differ by lender.
USE
Many needs
Cash flow, stock, equipment and growth.
OVERVIEW
An unsecured business loan lets you borrow without giving the lender any property or equipment as security. The lender looks at how your business is doing instead. That usually means your bank statements, your tax returns and your credit history.
Ahmedabad has many traders, shop owners, small manufacturers and service providers. Many of them need money for daily costs or growth but would rather keep their assets free. This loan type is made for them.
We are advisors. We help you see which lenders may suit your profile and explain the offers in plain words. The lender decides the loan amount and terms.
An unsecured business loan can help you
OUR AHMEDABAD OFFICE
Our Ahmedabad office
OUR AHMEDABAD OFFICE
OUR AHMEDABAD PARTNERS
Visit our Ashram Road office or call us. We will tell you which lenders may fit your business.
BENEFITS
We make business funding easier to understand and arrange.
You can borrow without pledging property or equipment.
We keep the paperwork clear and tell you what is needed.
Our team is in Ahmedabad. Visit, call or write to us.
Tell them about us. We will help them explore their loan options.
ELIGIBILITY
Many business owners can apply. Each lender has its own rules.
What do lenders look at?
Lenders want to see a stable business and a sound financial record.
You sell goods and need money for stock or daily costs. Lenders look at your sales and bank record. Each lender has its own rules.
Bank statements
Last 3 months
Tax returns
Last 3 years
ID and address proof
Standard papers
Best for
Stock and short-term needs
You earn from services and need money to run or grow. Lenders look at how steady your income is.
Bank statements
Last 3 months
Tax returns
Last 3 years
ID and address proof
Standard papers
Best for
Cash flow and growth plans
You run a partnership, LLP or private limited company. Lenders check the business record and its finances.
Bank statements
Last 3 months
Tax returns
Last 3 years
ID and address proof
Standard papers
Best for
Expansion and equipment
Work out your EMI and get the exact list of papers lenders ask for.
For planning only. Your lender confirms the final EMI.
RATES, FEES AND CHARGES
Costs depend on the lender and your business. We explain every charge before you decide.
Item
Typical
Notes
Interest rate
Set by the lender
Depends on your profile
Security
None
You do not pledge assets
Loan amount
Set by the lender
Based on your papers and turnover
Repayment time
Flexible
Options vary by lender
Charges
As the lender states
We list them clearly before you sign
BEFORE YOU APPLY
A little preparation helps your file move faster.
Be clear on what the money is for.
Lenders read your statements closely.
Keep the last 3 years ready.
A stable record can help.
Match EMI to cash flow
Pick a payment you can keep up.
Know the full cost before you sign.
RELATED LOANS
Not sure this is the right fit? See these options.
How we work
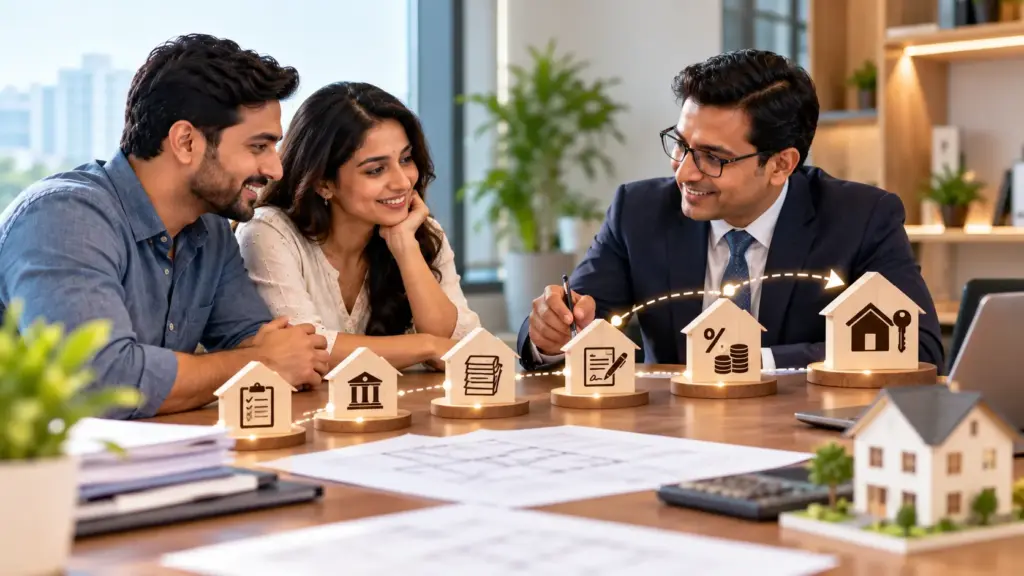
At every step you know what is happening, who is handling it and what you get at the end of it.
01
We review your income, credit history, property and existing loans, and tell you honestly what is possible.
who
You + your advisor
You get
A clear view of what is possible
02
We shortlist the banks and NBFCs whose policies fit your profile, so you apply where approval is likely.
who
You + your advisor
You get
A clear view of what is possible
03
We give you one checklist, collect the papers and check them before the lender sees your file.
who
You + your advisor
You get
A clear view of what is possible
04
We present your case to the chosen lender and handle their questions on your behalf.
who
You + your advisor
You get
A clear view of what is possible
05
We compare the sanction terms and negotiate rate, fees and conditions where possible.
who
You + your advisor
You get
A clear view of what is possible
We follow up on legal, valuation and agreement steps until the money reaches you.
who
You + your advisor
You get
A clear view of what is possible
CASE STUDY
From a client’s own words on our website.
WORKING CAPITAL ENHANCEMENT
A Mumbai-based engineering components manufacturer with ₹60 Cr turnover and 12 years in business. Its existing ₹4 Cr cash credit limit no longer matches its order book.
Our approach: assess the working capital need from audited financials, the stock and debtor cycle, and the order pipeline. Then propose increasing the limit to ₹8 Cr, backed by stock and book debts, with the factory land and building as additional security.
Client
Engineering manufacturer, Mumbai
Turnover
₹60 Cr
Structure
Cash credit enhancement (₹4 Cr → ₹8 Cr)
Security
Factory land & building, valued ~₹12 Cr
Posted on Google
 Dev singh
Trustindex verifies that the original source of the review is Google.
Smooth process along with correct guidancePosted on Google PRATIK SHAHNihal Fintech helped alot throughout the process and provided complete support especially Rajesh More and Niral mehta. Really thanks for helping us throughout and help us to achieve our dream of having house in Mumbai.Posted on Google
 Harsshal GosaviVery professional and reliable finance consultant. Clear guidance, quick response, and transparent process. Highly recommended for loans and financial solutions.Posted on Google
 Vikas Ambade
Trustindex verifies that the original source of the review is Google.
All documentation work was completed on time; thanks for the team.
MSMEs, sole proprietors, partnership firms, LLPs, private limited companies, retailers, traders, and service providers are eligible to apply, depending on the lender’s requirements.
No, unsecured business loans do not require collateral. Approval is based on financial stability and business performance.
Startups with verifiable revenue and valid financial documentation may be considered, depending on lender policies.
Funds can typically be used for working capital, inventory purchases, marketing, equipment upgrades, vendor payments, expansion, or operational requirements.
Lenders decide loan limits based on the applicant’s financial documents, income stability, business turnover, and internal policies.
Share a few details and an advisor will call you to check feasibility. Or call us on +91 77009 44833.