Home » Industries » Loans for Doctors & Clinics
Borrow to buy, build or renovate a home. We compare interest rates, processing fees and eligibility across leading banks and HFCs in Mumbai and Ahmedabad so you get the most competitive loan for your profile.
OVERVIEW
A home loan is an amount of money borrowed from a bank, payable in EMI over an agreed period. The home you buy is the security for the loan, which is why home loans usually cost less than unsecured borrowing.
You can choose a fixed interest rate for predictable monthly payments, or a floating rate that moves with the lender’s benchmark rate. Home loans can be used for a residential purchase, land acquisition, renovation, or a balance transfer of your existing home loan.
The loan is usually disbursed to the seller or builder: in one go for a ready home, or in stages as construction progresses for an under-construction home. You start paying full EMIs once the loan is fully disbursed; before that, many lenders charge interest only on the amount released.
As your advisor, we look at your income, credit history, existing loans and the property, then shortlist the banks and housing finance companies whose policies fit you. We prepare your file, compare the offers and assign a dedicated planner to your case.
A home loan is right for you if
WHO CAN APPLY
Buying with a home loan keeps your savings free and spreads the cost over years. It also gives you tax deductions and helps you build credit.
The government allows you to reduce your taxable income through principal repayment and interest, with deductions under Section 80C and Section 24(b).
Home loans usually have lower interest rates compared to other borrowings like car loans or personal loans, keeping repayment manageable.
With a flexible home loan tenure up to 30 years, you pay a smaller amount back each month, making it easier to manage your household budget.
With a flexible home loan tenure up to 30 years, you pay a smaller amount back each month, making it easier to manage your household budget.
With a flexible home loan tenure up to 30 years, you pay a smaller amount back each month, making it easier to manage your household budget.
With a flexible home loan tenure up to 30 years, you pay a smaller amount back each month, making it easier to manage your household budget.
Partner with Nihal Fintech or refer someone through Refer & Earn, with rewards starting from ₹2,500 up to lakhs*.
A few simple checks before you submit your application save time and protect your credit score.
Since loans run for years, use our home loan EMI calculator before you decide.
Applying for too much can cause rejection. Aim for an amount that matches your verifiable income.
An existing banking relationship can speed up the process, with simple KYC documentation.
A clean credit history can unlock faster approvals and preferential interest rate tiers.
For higher loan amounts, a co-applicant can increase eligibility or extend the tenure.
Calculate an EMI you can pay every month without straining your household budget.
OUR SOLUTIONS
For individuals, NRIs and businesses. We compare lenders for each product and recommend the best fit for your profile.
Work out your EMI and get the exact list of papers lenders ask for.
For planning only. Your lender confirms the final EMI.
ELIGIBILITY
Eligibility depends on your credit score, income profile and loan tenure. Each lender sets its own criteria; we match your profile to the ones that fit.
How much can I borrow?
Your loan amount depends mainly on:
From the medical council you are registered with
Degree certificates
Your qualifications (MBBS, MD, BDS or others)
PAN card and Aadhaar card
ITRs with computation of income
Practice and personal accounts
Ownership or rent agreement for the clinic premises
ELIGIBILITY
Eligibility depends on your credit score, income profile and loan tenure. Each lender sets its own criteria; we match your profile to the ones that fit.
How much can I borrow?
Your loan amount depends mainly on:
Eligibility is governed by your net monthly income, existing loan dues, age, and property valuation. Each lender applies distinct criteria; our role is matching your profile to the most accommodating policy.
Legal name
Nihal Fintech Pvt. Ltd.
Legal name
Nihal Fintech Pvt. Ltd.
Legal name
Nihal Fintech Pvt. Ltd.
Legal name
Nihal Fintech Pvt. Ltd.
Why Nihal Fintech
Walking into a bank gets you that bank’s answer. Coming to us puts your profile in front of the lenders most likely to approve it.
BEFORE YOU APPLY
A few simple checks before you submit your application save time and protect your credit score.
Since loans run for years, use our home loan EMI calculator before you decide.
Applying for too much can cause rejection. Aim for an amount that matches your verifiable income.
An existing banking relationship can speed up the process, with simple KYC documentation.
A clean credit history can unlock faster approvals and preferential interest rate tiers.
For higher loan amounts, a co-applicant can increase eligibility or extend the tenure.
Calculate an EMI you can pay every month without straining your household budget.
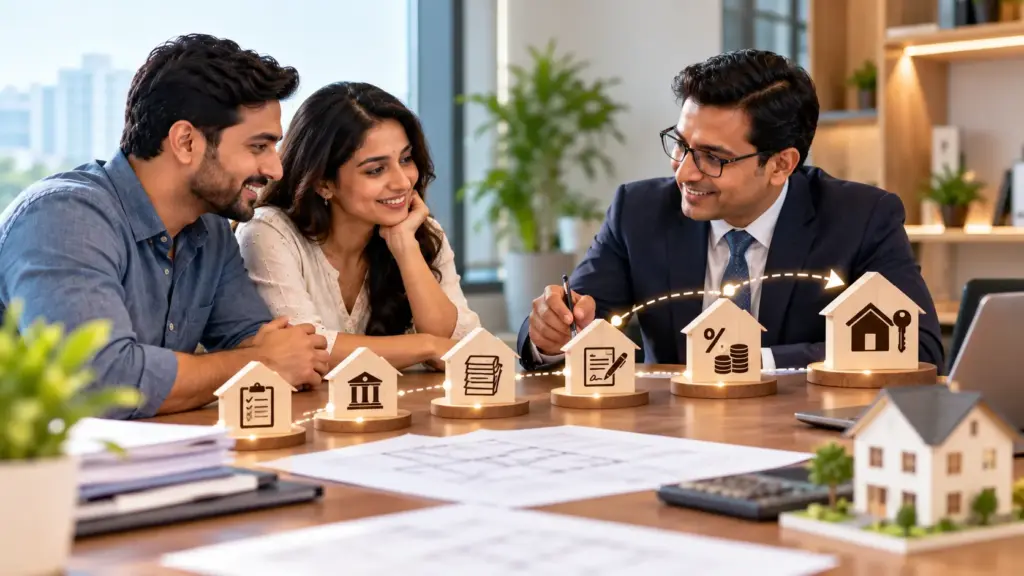
How we work
At every step you know what is happening, who is handling it and what you get at the end of it.
01
We review your income, credit history, property and existing loans, and tell you honestly what is possible.
who
You + your advisor
You get
A clear view of what is possible
02
We shortlist the banks and NBFCs whose policies fit your profile, so you apply where approval is likely.
who
You + your advisor
You get
A clear view of what is possible
03
We give you one checklist, collect the papers and check them before the lender sees your file.
who
You + your advisor
You get
A clear view of what is possible
04
We present your case to the chosen lender and handle their questions on your behalf.
who
You + your advisor
You get
A clear view of what is possible
05
We compare the sanction terms and negotiate rate, fees and conditions where possible.
who
You + your advisor
You get
A clear view of what is possible
We follow up on legal, valuation and agreement steps until the money reaches you.
who
You + your advisor
You get
A clear view of what is possible
Posted on Google
 Dev singh
Trustindex verifies that the original source of the review is Google.
Smooth process along with correct guidancePosted on Google PRATIK SHAHNihal Fintech helped alot throughout the process and provided complete support especially Rajesh More and Niral mehta. Really thanks for helping us throughout and help us to achieve our dream of having house in Mumbai.Posted on Google
 Harsshal GosaviVery professional and reliable finance consultant. Clear guidance, quick response, and transparent process. Highly recommended for loans and financial solutions.Posted on Google
 Vikas Ambade
Trustindex verifies that the original source of the review is Google.
All documentation work was completed on time; thanks for the team.
Home loan rates start at 8.5% p.a., depending on your credit score, income profile and loan tenure. The lender sets the final rate for your profile.
With a monthly salary of ₹50,000, you may be eligible for a home loan of approximately ₹25–30 lakh. Existing EMIs, credit score and the lender’s policy change the final amount.
Identity proof, address proof, income proof (salary slips or ITR), bank statements and property documents. Your advisor gives you the exact list for your lender.
Usually 3–7 working days when your documents are complete and your credit score is strong.
A credit score above 750 gets you the best rates and fastest approvals. If your score is lower, some NBFCs and housing finance companies may still evaluate your profile with a higher down payment or an eligible co-applicant. Our advisors can evaluate which lenders match your situation.
Up to 30 years, which keeps the monthly EMI smaller.
Floating rates are generally lower and have no prepayment penalties for individual borrowers as per RBI rules. Fixed rates offer EMI certainty but usually carry a higher interest rate. Most borrowers choose floating rates, but we help you compare both options.
Yes. The lender releases the loan in stages as construction progresses, and checks the project’s approvals before sanction.
Yes. For higher loan amounts, adding a co-applicant can increase your eligibility or let you choose a longer tenure.
Yes. We specialise in NRI financial services and manage the documentation locally.
No. All processing fees, interest rates and bank charges are clearly explained upfront.
When the saving in interest from moving your loan to another lender is clearly more than the cost of moving (processing, legal and valuation charges). Your advisor compares the new offer with what you pay today before you switch.
Your credit report and score, income and its stability, existing EMIs, age, and the property’s legal title and valuation. A complete file with clear property papers speeds up the sanction.
Share a few details and an advisor will call you to check feasibility. Or call us on +91 77009 44833.