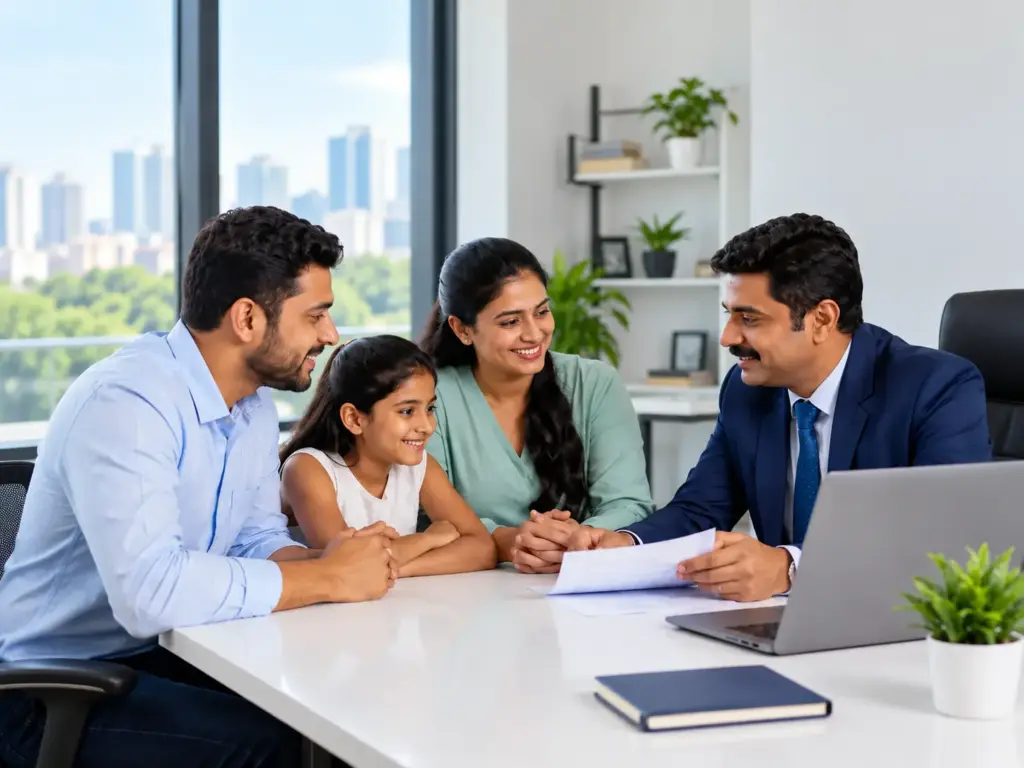
Want to protect your family, your health or your car? We help you compare insurance plans and pick one that fits your budget. We work with insurers registered with IRDAI, the insurance regulator. The insurer issues the policy. We help you understand the coverage and choose a suitable plan with confidence.
PLANS WE COVER
Life, health and motor
Also home, travel and business insurance.
HOW WE HELP
We compare for you
You see plans from several insurers.
ADVICE
Independent
We are not tied to one insurance company.
EXPERIENCE
12+ years
In financial services, with an office in Kandivali West.
OVERVIEW
Insurance is a simple deal. You pay a small amount, called a premium. In return, the insurer pays for certain big costs, like a hospital bill, an accident or damage to your property.
Life in Mumbai can be costly, and one bad day can hurt your savings. The right plan gives you and your family a safety net. It can also help you save tax.
We are not an insurance company. We are advisors. We explain your options in plain words, compare plans, and help you choose.
Insurance can help you pay for
OUR MUMBAI OFFICE
Our Mumbai office
OUR MUMBAI OFFICE
PLANS WE COVER
Come to our office or call us. We will help you find the cover you need.
BENEFITS
A good plan protects your money and gives you peace of mind.
Insurance helps protect your finances from unexpected medical bills, accidents, and other covered expenses.
Health insurance helps cover eligible medical and hospitalisation expenses, reducing your out-of-pocket costs.
Life, motor, home, and business insurance can help safeguard your loved ones and valuable assets against covered risks.
Tell them about us. We will explain the options in simple words.
FIND YOUR COVER
Anyone can buy insurance. The right plan depends on your age, your family and your budget.
How much cover do I need?
A common rule of thumb is to get life cover of 10 to 15 times your yearly income. Add any loans you still have.
Life insurance protects your family if you are not there. Term insurance gives cover at a low cost. Other plans, like endowment or ULIP, mix cover with savings.
Term plan
Pure cover, usually the lowest cost
Whole life
Covers you for life, but costs more
ULIP and endowment
Cover plus savings
Check
Claim settlement ratio of the insurer
Health insurance helps pay for hospital bills. You can buy a plan for yourself, a family plan or a plan for senior parents.
Types
Single, family floater, senior citizen
Network hospitals
Check that your hospitals are on the list
Waiting periods
Some illnesses are covered only after a wait
Check
What the plan does not cover
Motor insurance covers your car or bike. It is required by law in India. A full plan can also cover damage to your own vehicle and theft.
Third-party cover
Required by law
Full cover
Also covers your own vehicle
Vehicles
Car and two-wheeler
Check
What the plan does not cover
PREMIUMS AND CHARGES
The price of a plan depends on a few simple things. We explain each one before you buy.
Item
What it means
Notes
Your age
Older age means a higher premium
Buying early usually costs less
Cover amount
More cover means a higher premium
Pick what you really need
Health and habits
Smoking and health issues can raise the premium
Always tell the truth
Type of plan
Term costs less than whole life
Pick by need, not only by price
Exclusions and waiting periods
Things the plan does not cover, or covers later
Read these before you buy
BEFORE YOU BUY
A few easy steps can help you avoid mistakes.
Decide who and what you want to protect.
Look at plans from more than one IRDAI-registered insurer.
See how often the insurer pays claims.
For health plans, check that your hospitals are on it.
Read the exclusions
Know what is not covered and any waiting periods.
Premiums rise as you get older.
RELATED SERVICES
We also help with loans. Take a look.
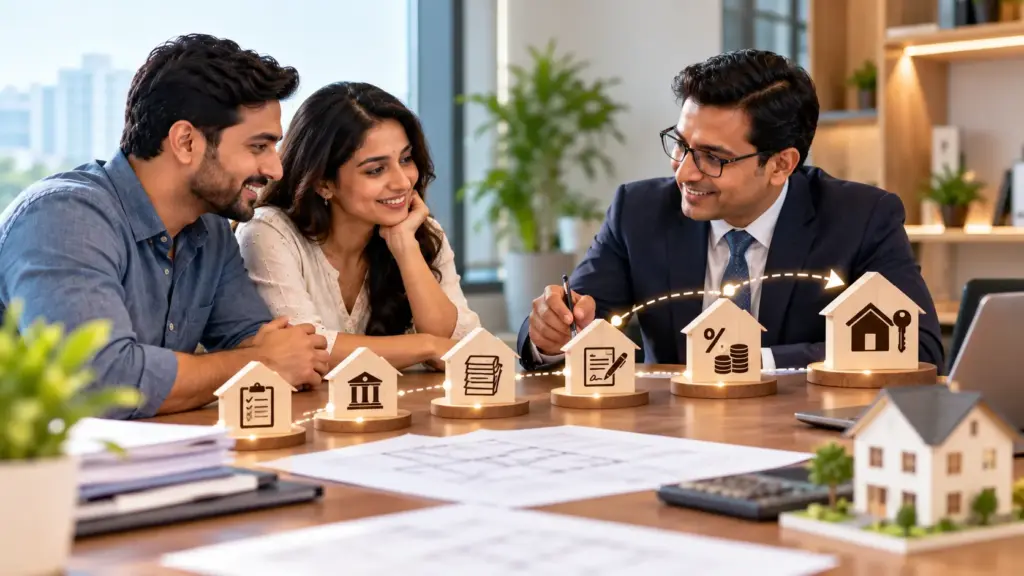
How we work
At every step you know what is happening, who is handling it and what you get at the end of it.
01
We look at your income, credit history, assets and existing loans, and tell you honestly what is possible.
who
You + your advisor
You get
A clear idea of what you can get
02
We pick the banks and finance companies whose rules fit your profile, so you apply where approval is likely.
who
Your advisor
You get
A short list of lenders
03
We give you one checklist, collect your papers and check them before the lender sees your file.
who
You + your advisor
You get
A complete, checked file
04
We present your case to the chosen lender and handle their questions for you.
who
Your advisor
You get
No need to chase the lender
05
We compare the offers and try to get you better rates, fees and terms where possible.
who
Your advisor
You get
Offers you can compare
We follow up on the final steps until the money reaches you.
who
You + your advisor
You get
Funds in your bank account
CASE STUDY
A recent case from our work.
WORKING CAPITAL ENHANCEMENT
A Mumbai-based engineering components manufacturer with ₹60 Cr turnover and 12 years in business. Its existing ₹4 Cr cash credit limit no longer matches its order book.
Our approach: assess the working capital need from audited financials, the stock and debtor cycle, and the order pipeline. Then propose increasing the limit to ₹8 Cr, backed by stock and book debts, with the factory land and building as additional security.
Client
Engineering manufacturer, Mumbai
Turnover
₹60 Cr
Structure
Cash credit enhancement (₹4 Cr → ₹8 Cr)
Security
Factory land & building, valued ~₹12 Cr
Posted on Google
 Dev singh
Trustindex verifies that the original source of the review is Google.
Smooth process along with correct guidancePosted on Google PRATIK SHAHNihal Fintech helped alot throughout the process and provided complete support especially Rajesh More and Niral mehta. Really thanks for helping us throughout and help us to achieve our dream of having house in Mumbai.Posted on Google
 Harsshal GosaviVery professional and reliable finance consultant. Clear guidance, quick response, and transparent process. Highly recommended for loans and financial solutions.Posted on Google
 Vikas Ambade
Trustindex verifies that the original source of the review is Google.
All documentation work was completed on time; thanks for the team.
Nihal Fintech provides advisory services for life insurance (term, endowment, ULIPs), health insurance (individual, family floater, senior citizen), motor insurance (car and two wheeler), home insurance, travel insurance, and business insurance. We compare plans from all major IRDAI-registered providers – including LIC, HDFC Life, Max Life, Star Health, Care Health, and Bajaj Allianz – to recommend the policy that genuinely fits your needs and budget. As independent advisors, we’re not tied to any single company, so our recommendations are unbiased.
Term insurance provides pure life coverage at the lowest cost and is ideal for income replacement. Whole life insurance covers you until age 99–100 and builds cash value, but costs 5–10× more than term. For most working professionals in Mumbai with dependents, financial planners recommend a high-coverage term plan (₹1–2 crore) as the foundation, supplemented by health insurance and optional investment-linked plans for wealth creation. A ₹1 crore term plan for a healthy 30- year-old costs approximately ₹10,000–₹12,000 per year.
Claim Settlement Ratio (CSR) is the percentage of claims an insurance company approves out of total claims received in a financial year. A higher CSR means the insurer is more likely to pay your claim when you need it. For life insurance, look for CSR above 97%. As per IRDAI’s 2023-24 Annual Report, top CSR performers include: Max Life (99.34%), HDFC Life (98.55%), and LIC (98.74%). For health insurance, check the Incurred Claim Ratio (ICR) a ratio of 50–80% is considered healthy, indicating the insurer pays out a fair share of premiums as claims.
Yes. Most health insurers in India cover pre-existing conditions after a mandatory waiting period of 2–4 years, as mandated by IRDAI guidelines. It’s essential to disclose all pre-existing conditions (diabetes, hypertension, thyroid disorders, etc.) during the application. Non-disclosure can lead to claim rejection. Some insurers like Star Health and Care Health offer plans with shorter waiting periods (2 years) for specific conditions. Our advisors at Nihal Fintech can identify the best plan for your health profile.
Financial experts recommend life insurance coverage equal to 10–15× your annual income, plus outstanding liabilities. A Mumbai professional earning ₹12 lakh/year should ideally have ₹1.2–1.8 crore in life cover. Factor in: outstanding home loan balance, children’s education costs (₹20–50 lakh for professional degrees), spouse’s financial independence timeline, and ageing parents’ medical expenses. At Nihal Fintech, we help calculate your precise coverage needs through a personalised Human Life Value (HLV) assessment.
Life insurance premiums qualify for tax deductions under Section 80C of the Income Tax Act (up to ₹1.5 lakh/year). Health insurance premiums are deductible under Section 80D ₹25,000 for self and family, plus ₹50,000 for senior citizen parents. Additionally, maturity proceeds from life insurance policies are tax-free under Section 10(10D) if the annual premium doesn’t exceed 10% of the sum assured. NPS (National Pension System) contributions qualify for an additional ₹50,000 deduction under Section 80CCD(1B). Combined, a Mumbai taxpayer can save ₹50,000–₹75,000 annually through strategic insurance and retirement planning.
Nihal Fintech Pvt. Ltd. is a financial advisory and consultancy firm not an insurance company. We operate as independent insurance advisors who partner with multiple IRDAI-registered insurance providers to offer unbiased, comparison-based guidance. Established on June 29, 2013, and headquartered at 405 Mahalaxmi Centre, Kandivali West, Mumbai, we serve clients across Mumbai and Pune. Our model ensures we recommend the insurer and plan that genuinely fits your needs because we’re compensated as advisors, not agents of any single company.
Share a few details and an advisor will call you to check feasibility.
Or call us:
Mumbai: +91 77009 44833
Ahmedabad: +91 99985 84455